
Imagine your payment processor holds $2 million in customer crypto. Now imagine that platform goes bankrupt tomorrow. Where does that money go? In traditional banking, you have FDIC insurance. In crypto billing, if the custodian fails, you are just another unsecured creditor in a messy legal queue. This is why holding customer funds has become the single biggest liability for any business processing digital asset payments.
For years, the standard model for crypto billing involved platforms taking custody of assets. They would pool customer deposits into hot wallets, manage the private keys, and settle merchants on their own schedule. It felt convenient. But convenience came with a hidden cost: massive balance-sheet exposure. Today, regulators from the U.S. SEC to the EU’s MiCA framework treat this custody not as a service feature, but as a primary source of financial risk. If you control the keys, you own the liability when things go wrong.
The Anatomy of Custody Risk
To understand the danger, we need to look at what actually happens when a platform takes custody. Crypto custody is the storage and management of private keys that prove ownership of digital assets. When a billing platform acts as a custodian, it becomes the sole gatekeeper to those assets. There is no reset button. If a key is lost, stolen, or compromised, the assets are gone forever. Unlike a bank account where a manager can freeze a transaction or reverse an error, blockchain settlements are irreversible. This finality cuts both ways: it protects users from fraud by the platform, but it exposes them to total loss if the platform itself fails.
The risks break down into three core categories:
- Key Management Failure: Private keys must be generated, stored, and backed up securely. A single misstep in access control or backup procedure can lead to permanent loss. Auditors like PwC highlight that without strict segregation of duties, internal fraud or external hacks can drain pooled wallets instantly.
- Insolvency and Commingling: Many platforms use "omnibus" or pooled wallets. Legally, this often means customers hold a debt claim against the company rather than direct title to specific coins. If the company collapses, those funds get mixed with corporate cash. Customers compete with other creditors for whatever remains, often recovering only a fraction of their value.
- Regulatory Intervention: Governments can freeze assets, shut down operations, or impose new capital requirements overnight. If a regulator steps in, customer funds may be locked in litigation for years while the platform’s operational costs continue to burn through reserves.
What Regulators Are Saying
Regulatory bodies have moved quickly to codify these risks. The shift isn't just theoretical; it's changing how companies must report their finances. In March 2022, the U.S. Securities and Exchange Commission (SEC) issued Staff Accounting Bulletin No. 121 (SAB 121). This rule instructed entities safeguarding crypto for users to recognize those assets on their balance sheets alongside a corresponding "safeguarding liability." Essentially, if you hold $10 million in customer crypto, you must record a $10 million liability. It turns every customer deposit into a direct obligation on the company’s books.
Europe took a similar path with the Markets in Crypto-Assets Regulation (MiCA). Under MiCA, crypto-asset service providers (CASPs) face direct liability for losses of client assets due to cyber-attacks, theft, or operational errors. The liability is capped at the market value of the assets at the time of loss. This means if a hack drains a wallet, the CASP owes the full amount back to the user, regardless of whether the hack was their fault or a sophisticated external attack. Canada tightened its rules further in early 2026, requiring detailed disclosures on storage and segregation, with explicit legal liability for negligence. Japan is even planning mandatory "liability reserves," forcing exchanges to keep capital buffers proportionate to client balances.
These rules create a heavy compliance burden. Companies must perform daily reconciliations, maintain strict segregation between client and corporate funds, and undergo continuous audits. For a billing platform processing high volumes, this overhead scales linearly with the amount of funds held. The more you hold, the more you risk, and the more you spend to protect it.
The Non-Custodial Alternative
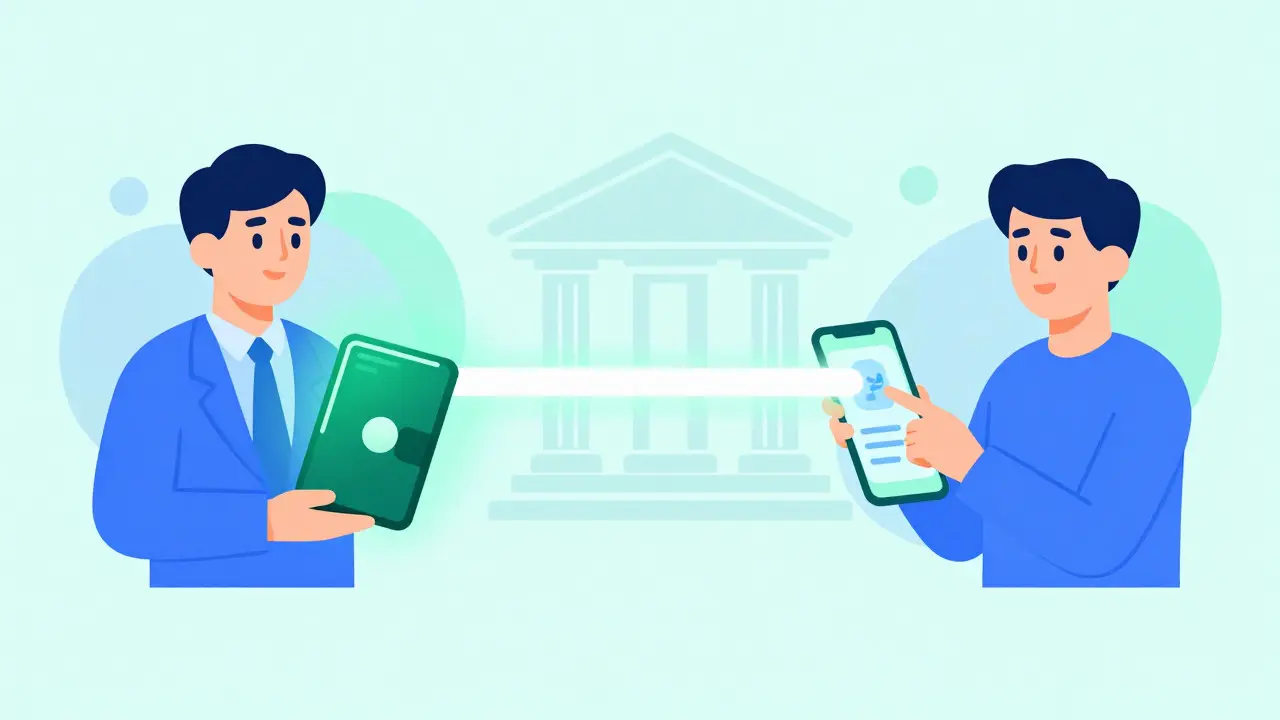
This is where the architecture of modern crypto billing is shifting. Instead of acting as a bank, many platforms are evolving into pure software infrastructure. A Non-custodial payment gateway is a system that routes payments directly from customer wallets to merchant-controlled addresses without ever holding the funds. In this model, the platform never touches the private keys. It doesn't pool assets. It doesn't owe a debt. It simply facilitates the handshake between sender and receiver.
How does this work technically? Most modern non-custodial gateways use extended public keys (XPUBs). The merchant connects their hardware wallet-like a Ledger or Trezor-to the dashboard. The gateway reads the public keys, which are safe to share, and derives unique receiving addresses for each invoice. When a customer pays, the transaction goes straight from their wallet to the merchant's wallet on-chain. The gateway monitors the blockchain for confirmation and triggers a webhook to update the merchant's website. At no point do the funds sit in a platform-controlled account.
| Feature | Custodial Model | Non-Custodial Model |
|---|---|---|
| Fund Control | Platform holds private keys | Merchant holds private keys |
| Bankruptcy Risk | High (Unsecured creditor status) | None (Funds never enter platform) |
| Regulatory Burden | Heavy (Capital reserves, audits, SAB 121/MiCA) | Light (Software provider status) |
| Settlement Speed | Dependent on platform withdrawal policies | Instant on-chain settlement |
| Chargeback/Freeze Risk | Possible (Platform discretion) | Structurally Impossible |
Why Merchants Are Switching
For merchants, especially solo founders and small businesses, the math is simple. Why take on counterparty risk for a service that could be purely informational? In a custodial setup, a merchant might face payout delays, account freezes during regulatory reviews, or worst-case scenarios like the FTX collapse, where billions in customer assets vanished because they were commingled with corporate funds. In a non-custodial setup, the merchant is their own bank. The funds land in their hardware wallet immediately upon confirmation. There is no withdrawal process to wait for. There is no support ticket to file if the platform has a bug. There is no KYC hurdle to clear before accessing your own revenue.
This shift also simplifies integration for developers. Modern non-custodial tools, such as TxNod, are designed for speed and reliability. By using TypeScript SDKs and MCP-native integrations, developers can connect AI coding agents to generate invoices and handle webhooks automatically. The focus moves from managing financial risk to building product features. Since the platform doesn't hold funds, its liability is limited to uptime and correct invoicing logic, not the safety of millions in assets. This makes it an attractive option for indie hackers and vibe-coders who want to accept Bitcoin, Ethereum, or stablecoins without becoming payments infrastructure experts.
Navigating the Transition
If you are currently using a custodial processor, moving to a non-custodial model requires a few practical steps. First, ensure you have a reliable hardware wallet set up. This is your new source of truth for ownership. Second, choose a gateway that supports XPUB-based address derivation. This allows you to generate thousands of unique addresses without exposing your main wallet details. Third, test the webhook flow thoroughly. Since the gateway isn't holding funds, your backend must correctly listen for the `invoice.paid` event and update your order status accordingly. Finally, verify the addresses locally if possible. Some advanced SDKs allow you to re-derive the payment address from your own xpub to ensure the gateway hasn't tampered with it, adding an extra layer of trustless verification.
The industry is clearly moving away from centralized custody for billing purposes. As regulations tighten and consumer awareness grows, the expectation is shifting toward self-sovereignty. Platforms that continue to hold customer funds will face higher costs, stricter scrutiny, and greater reputational risk. Those that embrace the non-custodial model offer a cleaner, safer, and more efficient path for both merchants and consumers. In the end, the safest place for your customer's funds is in their own hands-or yours, if you're the merchant-never in the middleman's pocket.
Is holding customer crypto always illegal?
No, it is not illegal, but it is heavily regulated. You need proper licenses, insurance, and compliance frameworks (like MiCA or SEC guidelines) to operate legally. However, the legal burden is so high that many smaller players prefer non-custodial models to avoid these obligations entirely.
What happens to my funds if a custodial exchange goes bankrupt?
You typically become an unsecured creditor. Your funds may be frozen in court proceedings for months or years. Recovery depends on the remaining assets after paying off secured debts and operational costs, meaning you might lose a significant portion of your balance.
How do non-custodial gateways make money if they don't hold funds?
They charge subscription fees or small transaction fees for the software service. Since they aren't earning interest on idle balances or trading on spreads, their revenue model is simpler and more transparent, often based on flat monthly rates rather than percentages of volume.
Do I need a registered company to use a non-custodial gateway?
Often, no. Because the platform isn't acting as a financial intermediary, many non-custodial providers allow individuals, freelancers, and solo founders to sign up without extensive KYC or corporate documentation, making it easier for small operators to start accepting crypto.
Can I still use fiat settlement with a non-custodial gateway?
Yes, but it usually involves a separate step. The gateway handles the crypto-to-wallet transfer. If you want fiat, you either sell the crypto yourself on an exchange or use a third-party conversion service. The gateway itself doesn't hold the funds long enough to convert them internally.


Author
Ronan Caverly
I'm a blockchain analyst and market strategist bridging crypto and equities. I research protocols, decode tokenomics, and track exchange flows to spot risk and opportunity. I invest privately and advise fintech teams on go-to-market and compliance-aware growth. I also publish weekly insights to help retail and funds navigate digital asset cycles.